Mortgage Pre-Approval Explained: What First-Time Homebuyers Need to Know
Thinking about buying a home but not sure where to start? Start with your mortgage pre-approval.
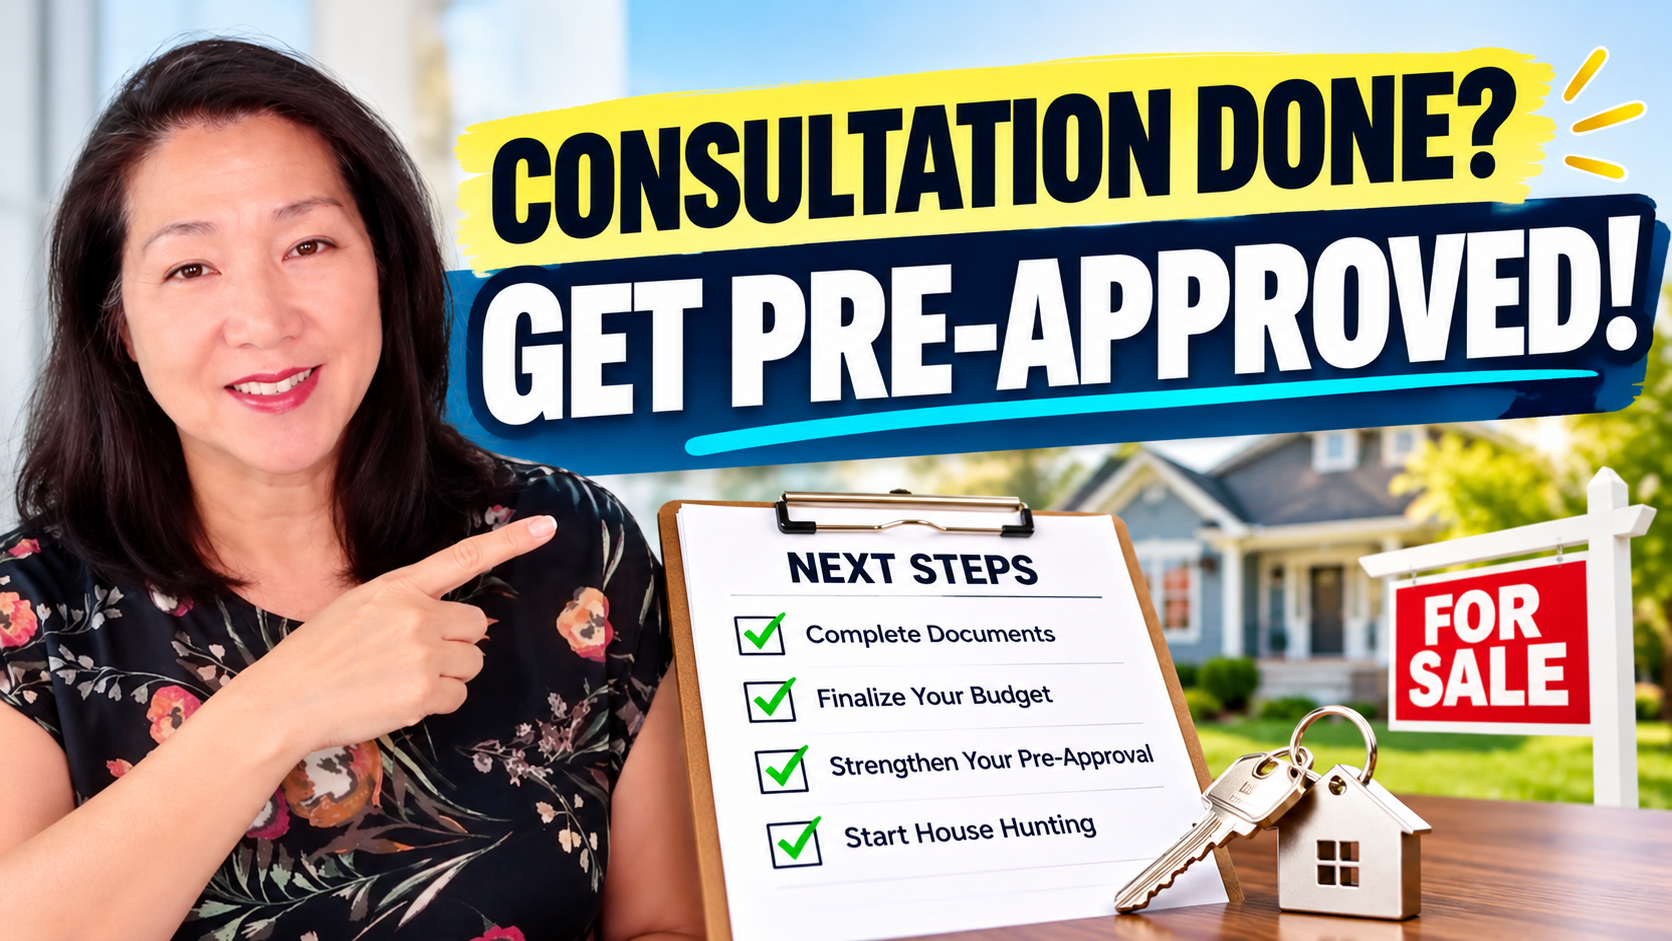
In this video, I break down why getting pre-approved should be your first step before you start looking at homes. A pre-approval answers 3 key questions:
✅ How much can you qualify for?
✅ How much are you comfortable spending?
✅ How much cash will you need to close?
Those first two numbers are NOT always the same, and knowing the difference can save you from becoming house poor.
During a pre-approval consultation, I review your income, debts, credit, available funds, and goals so we can build a realistic home buying budget. Not ready yet? No problem. We’ll map out exactly what needs to happen, whether that’s building savings, improving your credit, or finding out you’re in a stronger position than you thought.
👉 Where are you in the process? Ready to buy soon, 6 to 12 months out, or just exploring?
📅 Book a free 30-minute consultation: https://tidycal.com/paulinesolee/30-minute-meeting
📞 Call/Text: (508) 525-5415
📧 Email: Pauline@indmortgage.com
A mortgage pre-approval is an official evaluation by a lender that determines how much money you can borrow for a home loan based on your credit score, income, assets, and debt-to-income ratio. Getting pre-approved gives first-time homebuyers and real estate investors a clear purchase budget and strong bargaining power when submitting offers on homes.
A pre-qualification is an informal estimate of what you might be able to borrow based on self-reported financial information. In contrast, a mortgage pre-approval requires a comprehensive review of your official financial documents (like pay stubs, tax returns, and credit reports).
Lenders examine your gross monthly income, debt-to-income (DTI) ratio, credit score, and down payment savings. However, maximum loan qualification differs from personal affordability – your actual comfortable monthly housing budget should also factor in property taxes, home insurance, HOA fees, and lifestyle expenses.
Typically, you will need to provide proof of income (recent pay stubs, W-2s, tax returns), proof of assets for your down payment and closing costs (bank statements, investment accounts), a valid ID, and permission for the lender to pull your mortgage credit report.
Yes, investors can obtain pre-approval for investment property financing. Depending on the loan program (such as conventional, multi-family, or DSCR loans), lenders will evaluate your personal financial standing, existing real estate owned, or potential rental income generated by the target property.
Related Posts